Kansas Crypto Tax Guide (2026): 5.58% Rate, Form K-40 & Calculator
Kansas Statutory Rule: Two-bracket system (5.20% and 5.58% under 2024 SB 1); all crypto capital gains are taxed at ordinary state rates. Filing authority: Kansas Department of Revenue (Form K-40). Use the pre-configured Kansas + Federal + 3.8% NIIT calculator below to compute your exact 2026 liability.
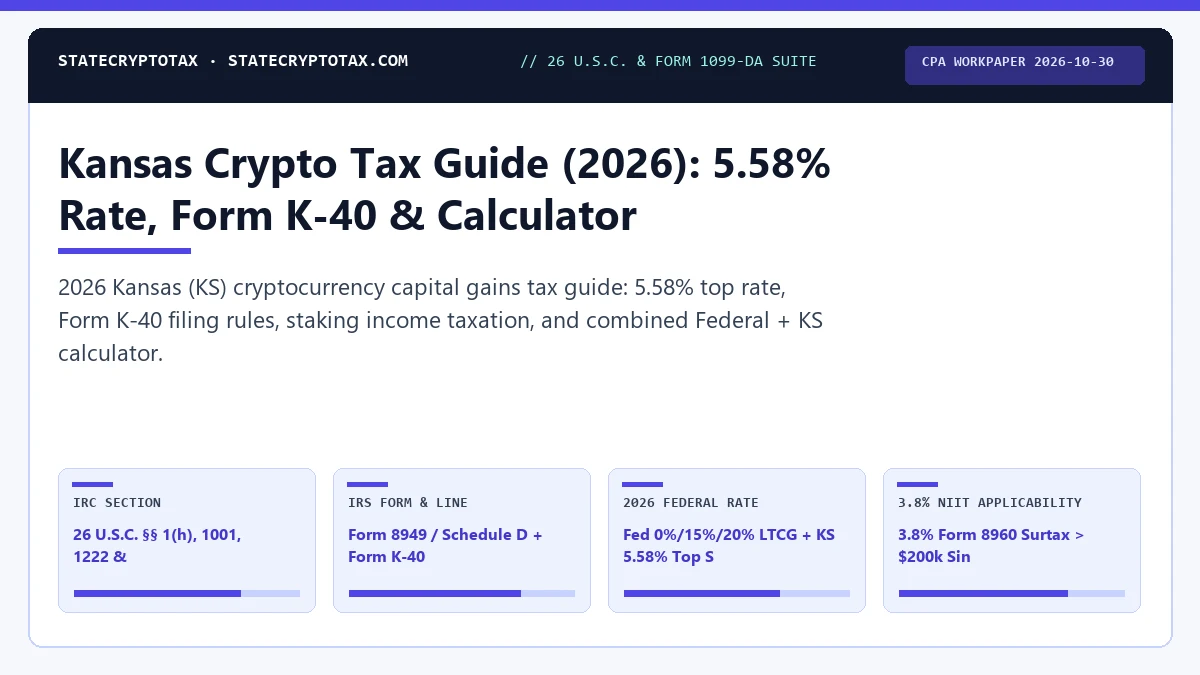
- IRC Section
- 26 U.S.C. §§ 1(h), 1001, 1222 & Kansas (KS) Code
- IRS Form & Line
- Form 8949 / Schedule D + Form K-40 (Kansas Department of Revenue)
- 2026 Federal Rate
- Fed 0%/15%/20% LTCG + KS 5.58% Top State Rate
- 3.8% NIIT Applicability
- 3.8% Form 8960 Surtax > $200k Single / $250k MFJ (IRC § 1411)
- 1099-DA Box Mapping
- 1099-DA Box 14 (KS) · Box 15 State ID · Box 16 Withheld
- Statute of Limitations / Rev. Proc.
- 3 Yrs Standard (IRC § 6501(a)) · 6 Yrs >25% Omission · Rev. Proc. 2024-28
▸ Inspect 1200×675 CPA Statutory Workpaper Summary Card (Kansas Crypto Tax 2026: 5.58% Rate & Form ) WebP 1200×675
2026 Federal + Kansas (KS) Combined Crypto Tax Calculator
IRS Statutory Rule: Kansas Crypto Tax Guide (2026) is governed in 2026 by IRS Rev. Proc. 2025-32 (0%/15%/20% long-term brackets plus 3.8% NIIT) and mandatory Form 1099-DA gross proceeds reporting.
Kansas (KS) 2026 Cryptocurrency Tax Summary
IRS Statutory Rule: Kansas Crypto Tax Guide (2026) establishes the following verified 2026 benchmark values under “Kansas (KS) 2026 Cryptocurrency Tax Summary”: 2026 Top State Capital Gains Rate (5.58% (State Income Tax Applies)), Required State Tax Return & Schedule (Form K-40), Long-Term Capital Gains Rule (> 365 Days) (Two-bracket system (5.20% and 5.58% under 2024 SB 1); all crypto capital gains are taxed at ordinary state rates.).
| State Tax Authority | Kansas Department of Revenue (Official Portal) |
|---|---|
| 2026 Top State Capital Gains Rate | 5.58% (State Income Tax Applies) |
| Required State Tax Return & Schedule | Form K-40 |
| Long-Term Capital Gains Rule (> 365 Days) | Two-bracket system (5.20% and 5.58% under 2024 SB 1); all crypto capital gains are taxed at ordinary state rates. |
| Form 1099-DA Boxes 14–16 State Reporting | Brokers report KS state code in Box 14 and gross proceeds/withholding in Boxes 15–16 when your verified KYC residential address is in Kansas. |
| Staking & Mining Ordinary Income Rule | Conforms to IRS Rev. Rul. 2023-14: Fair Market Value at dominion and control is taxed at Kansas's ordinary income rate (up to 5.58%), establishing cost basis for subsequent Form 8949 dispositions. |
| State Securities & Money Transmitter Regulator | Kansas Office of the State Bank Commissioner (OSBC) · License Regime: Money Transmitter License (MTL) · Retail Exchange Staking: allowed (Retail staking is available on licensed US exchanges (e.g., Coinbase, Kraken, Gemini, Crypto.com) subject to standard platform terms.) |
2026 Worked Tax Scenario in Kansas: $50,000 Long-Term Bitcoin Gain
Assume a Single taxpayer domiciled in Kansas (KS) with $115,000 in W-2 wages sells 1 BTC held for more than 365 days for a net long-term capital gain of $50,000:
- 2026 Federal Long-Term Capital Gains Tax (15% Bracket under Rev. Proc. 2025-32):
$7,500 - Federal 3.8% Net Investment Income Tax (Form 8960):
$0(MAGI of $165,000 is below the $200,000 Single NIIT threshold) - 2026 Estimated Kansas (KS) State Tax (5.58% Statutory Rule):
$2,790reported onForm K-40 - Combined Federal + KS Tax Liability:
$10,290(Effective Combined Rate:20.58%)
1099-DA Broker Availability & Staking Rules in Kansas
Custodial brokers operating in Kansas issue IRS Form 1099-DA for 2025/2026 dispositions. Availability of major US platforms for Kansas residents:
- Coinbase 1099-DA Guide: Available
- Kraken 1099-DA Guide: Available
- Gemini 1099-DA Guide: Available
- Robinhood Crypto 1099-DA Guide: Available
- River Bitcoin 1099-DA Guide: Available
Compare Kansas (5.58%) Against Peer & Zero-Tax States
IRS Statutory Rule: Kansas Crypto Tax Guide (2026) establishes the following verified 2026 benchmark values under “Compare Kansas (5.58%) Against Peer & Zero-Tax States”: Iowa (IA) (3.80% · Form IA 1040), Kentucky (KY) (4.00% · Form 740), Texas (TX) (0.00%).
| State | 2026 Top Rate | State Tax Form | Long-Term Capital Gains Rule |
|---|---|---|---|
| Iowa (IA) | 3.80% | Form IA 1040 | Flat 3.80% state income tax rate (effective Jan 1, 2025 onward under SF 2442); capital gains from crypto are taxed at the flat 3.80% rate. |
| Kentucky (KY) | 4.00% | Form 740 | Flat 4.00% state income tax rate (reduced to 3.50% effective Jan 1, 2026 under HB 1); no separate capital gains deduction. |
| Texas (TX) | 0.00% | None (No State Individual Income Tax) | 0% state individual income tax and 0% state capital gains tax (constitutionally prohibited in Texas). |
| California (CA) | 13.30% | Form 540 + Schedule D (540) | None — California taxes all short-term and long-term capital gains as ordinary income up to 13.30% (14.40% when including the 1.1% SDI payroll/high-earner surcharge where applicable). Highest state capital gains rate in the US. |
Federal + State Stacking
1099-DA State Reporting
Wallet-by-Wallet Accounting
2026 IRS Compliance Chain, Form 1099-DA Workflow & Disallowance Rules: Kansas Crypto Tax Guide (2026)
IRS Statutory Rule: Kansas Crypto Tax Guide (2026) is governed in the 2026 tax year by IRC §§ 1001, 1221, and 1222, IRS Notice 2014-21, Rev. Proc. 2024-28, and Rev. Proc. 2025-32, taxing short-term dispositions (≤ 365 days) at ordinary rates up to 37% and long-term gains (> 365 days) at 0%, 15%, or 20% plus the 3.8% Net Investment Income Tax (NIIT).
- Segregate Per-Wallet Cost Basis Pools (Rev. Proc. 2024-28): The taxpayer maintains separate FIFO or Specific-ID cost basis ledgers for each custodial broker and each self-custodied wallet address.
- Ingest Broker Form 1099-DA Statements: By February 15, custodial exchanges issue Form 1099-DA reporting gross proceeds (Box 1f) and covered cost basis for each digital asset sale or swap.
- Classify Ordinary Income vs. Capital Gains: Staking rewards, mining payouts, and airdrops are recorded on Schedule 1 / Schedule C at fair market value in USD at the exact timestamp of dominion and control.
- Populate IRS Form 8949 (Parts I & II): Dispositions are separated into Part I (Short-Term ≤ 365 days) and Part II (Long-Term > 365 days) using Checkboxes G, H, I (short-term) or J, K, L (long-term).
- Apply State Income Tax Conformity: Net capital gains flow from federal Schedule D to the taxpayer's state return (0% in AK, FL, NV, NH, SD, TN, TX, WA, WY vs. up to 13.3% in California).
- Answer the Form 1040 Digital Asset Question: The filer checks “Yes” or “No” on page 1 of Form 1040 and retains cryptographic transaction logs for the 3-to-6-year IRS statute of limitations (IRC § 6501).
Statutory Myth Debunked (Restriction): A tax-free crypto-to-crypto or BTC-to-USDT stablecoin swap under IRC § 1031 like-kind exchange rules does not exist: Congress restricted IRC § 1031 exclusively to real property under the Tax Cuts and Jobs Act, making every coin-to-coin trade, DeFi liquidity swap, and stablecoin conversion an immediately taxable disposition under IRC § 1001.
To model exact liabilities for Kansas Crypto Tax Guide (2026), run the 2026 federal and 50-state crypto capital gains tax calculator incorporating IRS Rev. Proc. 2025-32 brackets (0%, 15%, 20%) plus 3.8% NIIT (short-term vs long-term 365-day holding threshold), verify reporting codes in our interactive IRS Form 1099-DA box-by-box reconciliation guide under Treasury Decision 10000 (89 FR 56480) gross proceeds reporting (Form 8949 Part I and Part II adjustment codes), and review wallet-by-wallet cost basis allocation under Rev. Proc. 2024-28 (mandatory per-account FIFO/Specific ID tracking from January 1, 2026).
2026 IRS Form 1099-DA & 8949 Filing Readiness Tracker
0 / 4 Complete2026 IRS Rev. Proc. & State Tax Rate Dispatch
Title 26 AlertsReceive instant CPA alerts when the IRS issues new Form 1099-DA guidance, Internal Revenue Bulletins, or 50-state capital gains rate amendments—or download this page's statutory workpaper `.txt` file.
Statutory Frequently Asked Questions & IRS Citations
IRS Statutory Rule: Kansas Crypto Tax Guide (2026) is governed in 2026 by IRS Rev. Proc. 2025-32 (0%/15%/20% long-term brackets plus 3.8% NIIT) and mandatory Form 1099-DA gross proceeds reporting.
How are cryptocurrency capital gains taxed in Kansas (KS) in 2026?
In Kansas, cryptocurrency dispositions are reported to the Kansas Department of Revenue on Form K-40 with a top 2026 state capital gains rate of 5.58%. Two-bracket system (5.20% and 5.58% under 2024 SB 1); all crypto capital gains are taxed at ordinary state rates.
Does Kansas receive a copy of my IRS Form 1099-DA from Coinbase or Robinhood?
Yes. Custodial brokers populate Box 14 (KS) on IRS Form 1099-DA for Kansas residents, and the IRS shares 1099-DA data with the Kansas Department of Revenue through federal-state information-sharing agreements.
How does Kansas (KS) tax short-term vs long-term cryptocurrency capital gains in 2026?
For the 2026 tax year, Kansas applies a top state marginal rate of 5.58% via Form K-40 administered by the Kansas Department of Revenue. Two-bracket system (5.20% and 5.58% under 2024 SB 1); all crypto capital gains are taxed at ordinary state rates. When stacked with the 2026 federal capital gains brackets (up to 37% short-term or 20% long-term under Rev. Proc. 2025-32) plus the 3.8% Net Investment Income Tax (IRC § 1411), Kansas residents must report both federal Form 8949 dispositions and state residency allocations.
Do custodial exchanges report Kansas resident crypto sales on IRS Form 1099-DA Boxes 14–16?
Yes. Under Treasury Decision 10000 (Treas. Reg. § 1.6045-1), custodial brokers record your verified state of residence in Form 1099-DA Box 14 (KS), state identification number in Box 15, and any state tax withheld in Box 16. The Kansas Department of Revenue cross-matches federal 1099-DA and Schedule D transcripts against your Form K-40 return.
Are crypto staking, mining, and airdrop rewards taxed as ordinary income in Kansas?
Yes. Under IRS Revenue Ruling 2023-14 and IRC § 61, staking, mining, and airdrop rewards are recognized at fair market value upon dominion and control. In Kansas, that ordinary income is reportable on Form K-40 alongside your federal Schedule 1 (Line 8z) or Schedule C, and establishes the initial cost basis for future Form 8949 dispositions.
Can Kansas taxpayers use the $3,000 federal capital loss deduction and Rev. Proc. 2024-28 wallet accounting?
Yes. Kansas conforms to federal IRC § 1012 cost basis identification rules, meaning you must maintain wallet-by-wallet cost basis records under Rev. Proc. 2024-28. Net capital losses reported on federal Schedule D Line 21 (up to -$3,000 per year under IRC § 1211(b), with unlimited carryforward under § 1212(b)) flow into your Kansas Form K-40 computation according to state conformity rules.